Truck finance: what to sort before you talk to the dealer
Licence class, specs, running costs, budget and finance: what to work out before you walk into a truck dealer in Queensland, so you can negotiate on price.
 Jane BrookerFinance broker · Updated 6 October 2026 · 4 min read
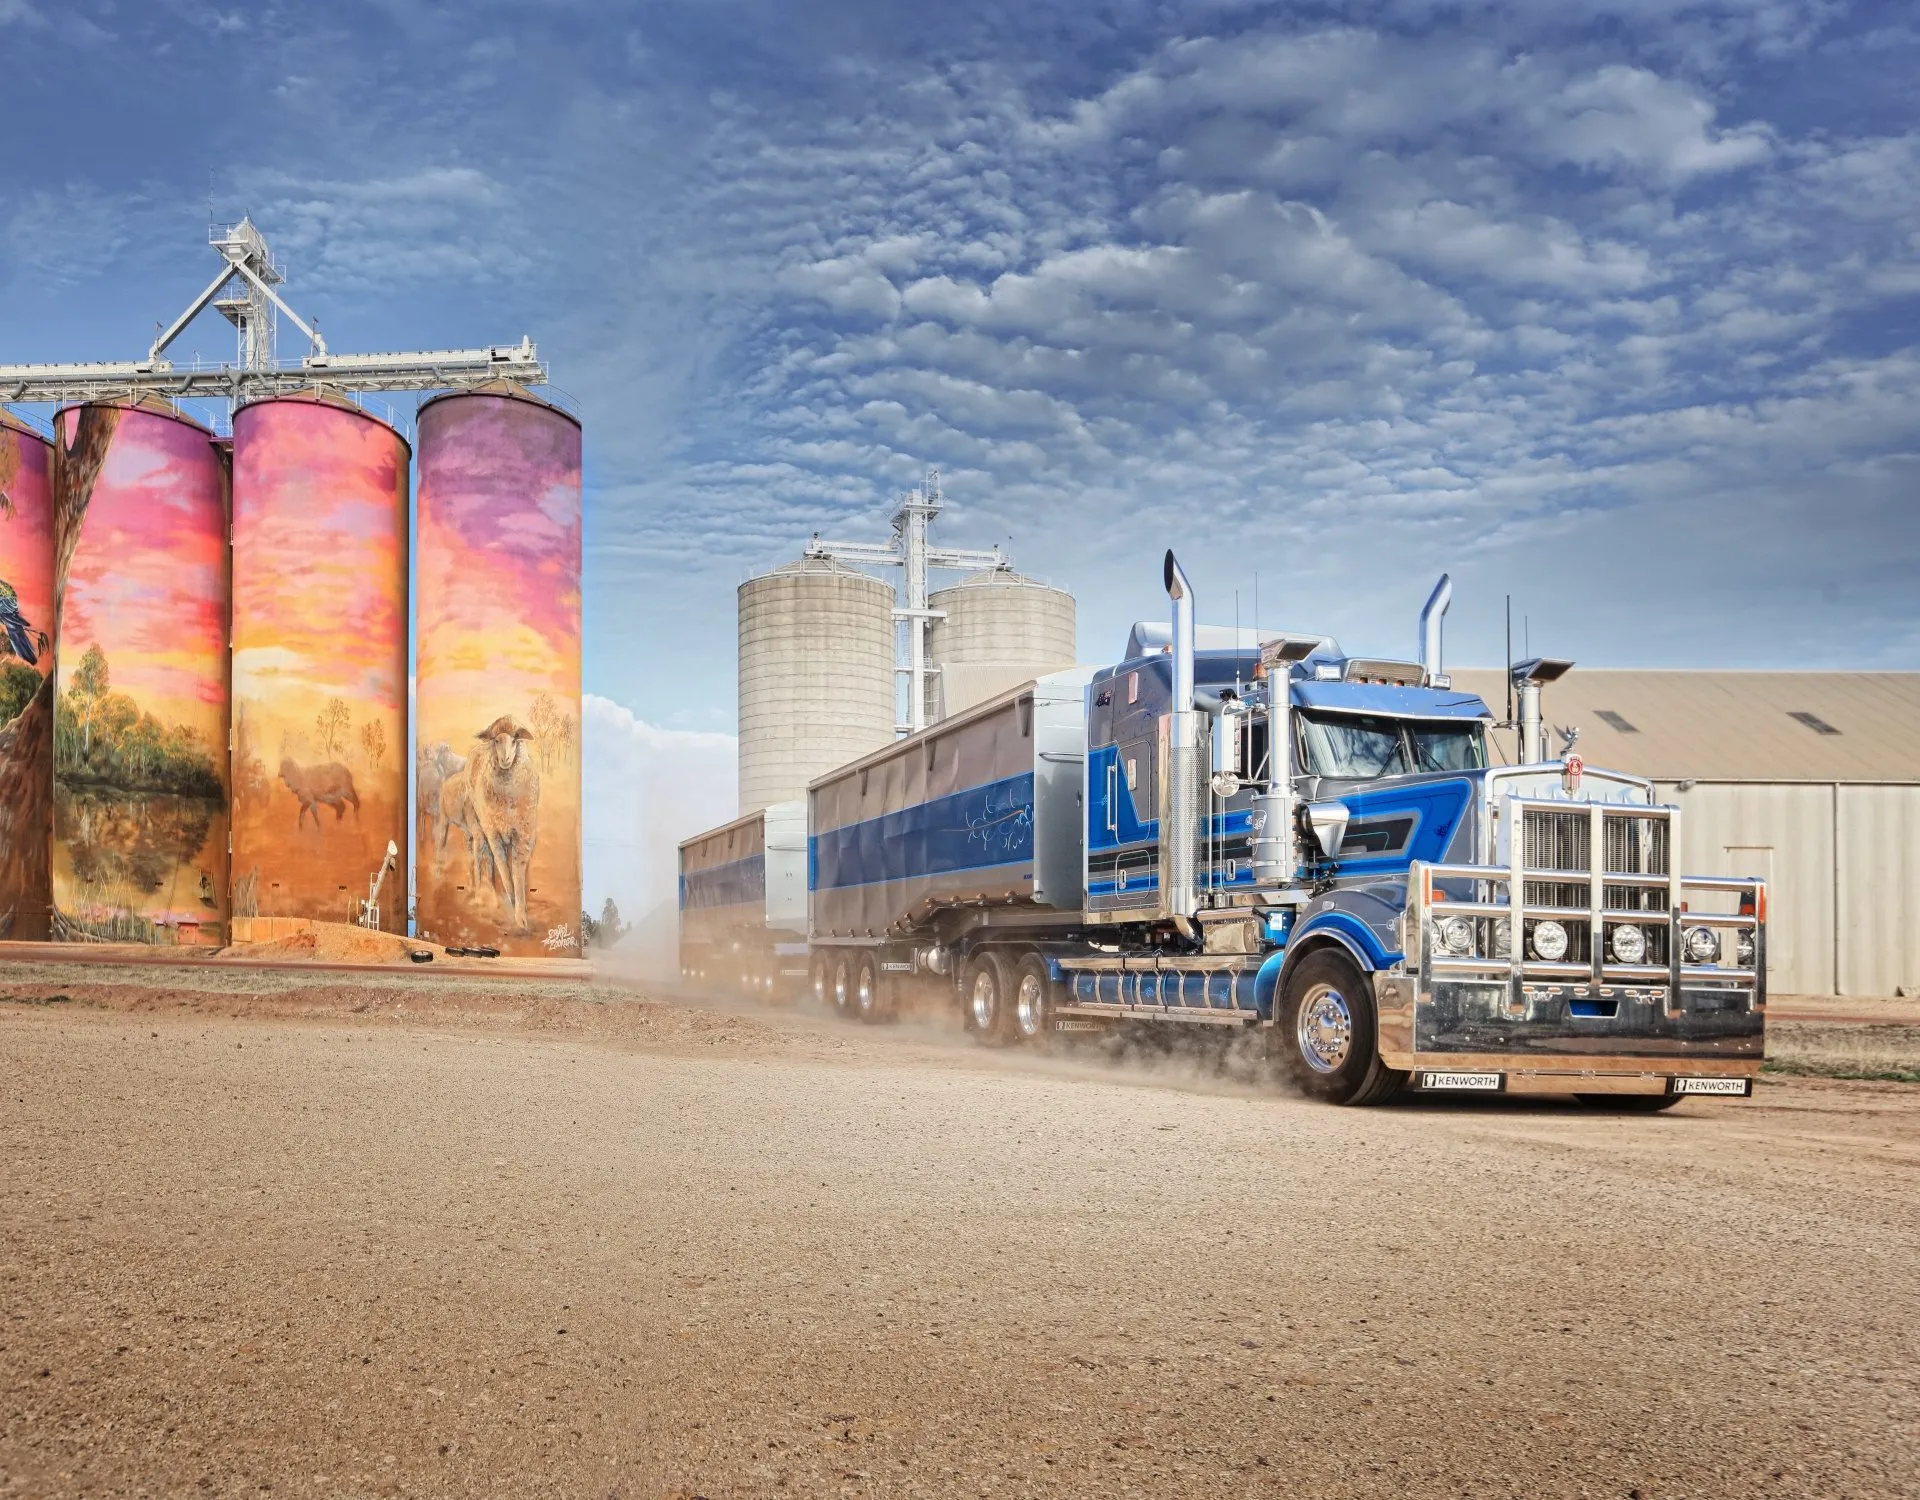
Before you visit a dealer, know the job, the truck’s specs, your licence class and your real budget, and line up your finance. Then you can compare the dealer’s finance offer with others and negotiate on the price of the truck, not the size of the repayment.
Truck dealers do this every day. Most buyers do it every few years. A little homework before you walk in puts you on an equal footing.
Here’s what I’d sort out first.
1. Start with the job
- What will it carry or pull, how far, and how often?
- What body does it need? A tipper, tray, pantech, tautliner, refrigerated body or a prime mover.
- What weights matter? The GVM (the most the truck can weigh loaded) decides your licence class and registration. The GCM matters if you tow a trailer.
- New or used? New means warranty and the latest safety gear. Used means a lower price, but more checks. Some lenders limit how old a truck can be by the end of the loan.
2. Check your licence class
In Queensland, the truck’s GVM and axles decide which licence you need.
| Class | What you can drive (in short) |
|---|---|
| C (car) | Vehicles up to 4.5 tonnes GVM |
| LR | Trucks up to 8 tonnes GVM |
| MR | Trucks over 8 tonnes GVM with 2 axles |
| HR | Trucks over 8 tonnes GVM with 3 or more axles |
| HC | Prime movers and heavy rigid trucks towing a trailer over 9 tonnes, like a semi-trailer |
| MC | B-doubles and road trains |
LR, MR and HR trucks can also tow a trailer up to 9 tonnes.
Upgrading takes time. You need to have held a car licence for 1 year before you can get an LR or MR licence, and 2 years before an HR. Each step after that needs a year in the class before. If you’re hiring drivers, check they hold the right class too.
3. Rego, inspections and the rules
- Heavy vehicles are those over 4.5 tonnes GVM. In Queensland, Transport and Main Roads registers them, and the charges are set nationally by the vehicle type and number of axles.
- An inspection every year. Heavy vehicles need a certificate of inspection before the rego can be renewed. A brand-new truck doesn’t need one in its first year, unless it changes hands.
- The national rules. The National Heavy Vehicle Regulator runs the Heavy Vehicle National Law, and does roadside checks in Queensland.
4. Work out your real budget
The price on the windscreen isn’t the whole cost. Budget for:
- The truck, including GST
- The body and fit-out, if it’s built separately
- Registration and registration duty (stamp duty)
- Comprehensive insurance
- Tyres, servicing, fuel, tolls and any permits
In Queensland, registration duty on a heavy vehicle is charged per $100 of value. As at October 2026, it’s $3.50 per $100 for a five or six-cylinder engine, $3 for four cylinders or fewer, $4 for seven or more, and $2 for hybrid and electric trucks. Check the Queensland Government’s duty page for the current rates.
Then decide on the structure. A deposit or trade-in lowers the loan. A longer term lowers the repayment but adds interest. A balloon lowers it further, but leaves a lump sum at the end. Read balloon payments explained, and test the numbers in my repayment calculator.
If your work is seasonal, think about the quiet months. The repayment has to work then too.
5. Line up your finance first
This is the big one. When your finance is sorted before you negotiate:
- You negotiate on price. You know what you can spend, so the conversation stays on the truck, not the repayment.
- You can compare. Dealer finance can be convenient. Compare its total cost and fees with what I find.
- You’re not deciding under pressure. Finance is a big commitment. It deserves more than ten minutes at the end of a sale.
What lenders look at for trucks:
- Your business: how long you’ve been trading, your recent figures and your credit history
- Your experience in transport, and any contracts or regular work lined up
- The truck: its age, kilometres, condition and body
- The deal: the price, deposit or trade-in, term and any balloon
Add-on insurance. Since October 2021, there’s a four-day wait before add-on insurance, like loan protection, can be sold to you with a vehicle. You don’t have to buy add-ons from the dealer. Moneysmart says add-on insurance is often poor value, so compare before you buy.
6. Before you sign
- The invoice shows the price, GST, body or fit-out, registration and on-road costs, and the VIN
- Finance approved in writing before you pay a deposit
- Used: a PPSR search for money owing, an inspection by a heavy vehicle mechanic, and the service records
- Used: the certificate of inspection is current
- The warranty in writing (see below)
- Insurance starts the day you pick it up
- You’ve spoken to your accountant about GST and depreciation
About warranties. In Queensland, trucks are “commercial vehicles”, so the dealer statutory warranty and cooling-off period for used cars don’t apply. The Australian Consumer Law guarantees still apply when you buy from a business. Ask exactly what warranty comes with the truck, and get it in writing.
Talk to me before the dealer
Call me before you start shopping. We’ll set a budget, look at lenders that know trucks, and line up the finance. Then you walk in ready.